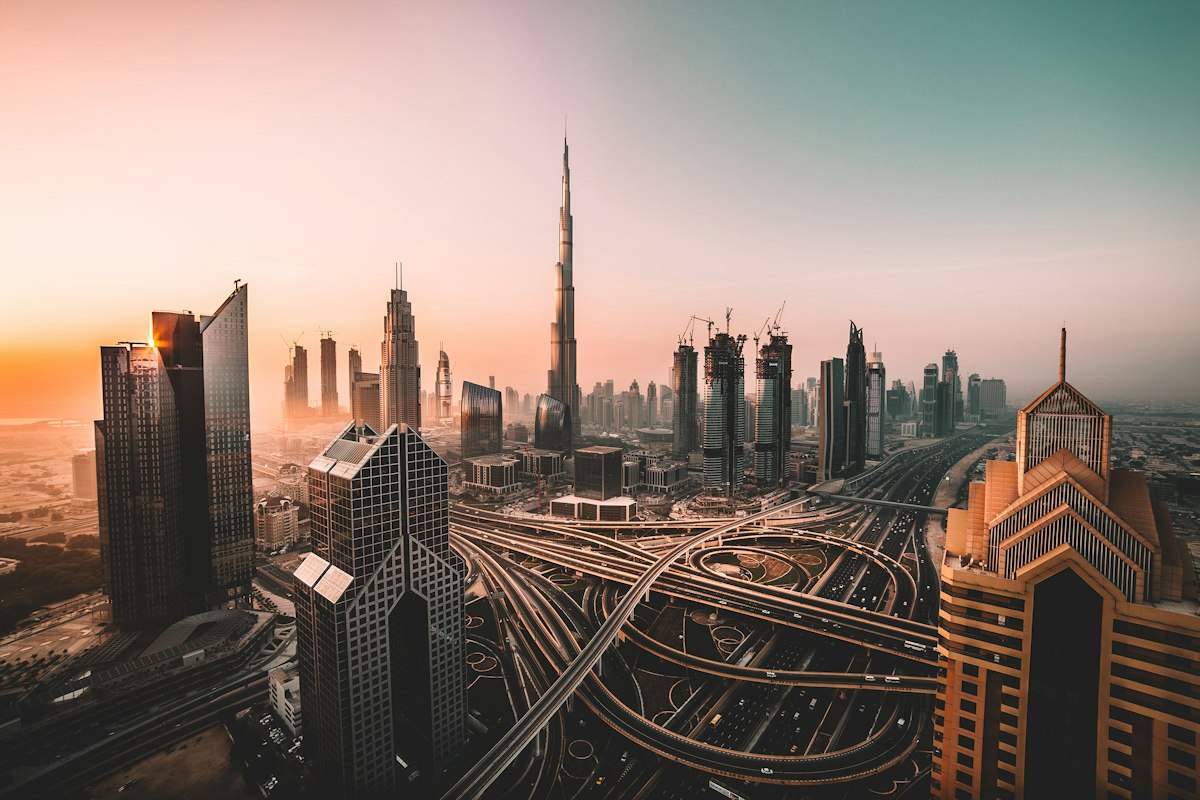
Top Fixed Rate Mortgage Options in Dubai for Expats
Buying a home in Dubai has shifted from a luxury dream to a practical financial strategy for many expats. With the city's population growing and rental prices in popular areas like Dubai Marina, Downtown, and Arabian Ranches reaching record highs, the argument for homeownership is stronger than ever. However, the transition from tenant to landlord comes with a significant hurdle: finding the right financing in a market that moves at lightning speed.
For most expatriates, the primary concern is stability. The UAE mortgage market is heavily influenced by the Emirates Interbank Offered Rate (EIBOR), which can fluctuate based on global economic shifts and US Federal Reserve decisions. This volatility makes fixed rate mortgages an attractive sanctuary for those who want to know exactly how much will leave their bank account every month without any surprises from the central bank.
Related posts
Understanding Non Resident Mortgage Interest Rates in Al Rajhi Bank for Property Investment
Securing a mortgage as a non-resident in Saudi Arabia often feels like navigating a complex financial maze. For...
Read more →Securing Your Home in Riyadh: The Murabaha Property Financing Process
Riyadh is currently the epicenter of a massive real estate transformation, driven by the ambitious goals of Vision...
Read more →
Using Sharia Compliant Home Financing Calculators Across Saudi Banks
When planning to purchase a villa, townhouse, or apartment in Riyadh, Jeddah, or the Eastern Province, your initial...
Read more →
Saudi Arabia Home Loan Requirements for Foreigners 2026
Saudi Arabia’s skyline is transforming at a pace that few predicted a decade ago. For expats living in...
Read more →Finding the best fixed rate mortgage in Dubai for expats involves more than just looking at the lowest headline percentage. You have to account for the length of the fixed term, the reversion rate once that term ends, and the often-overlooked fees that can add thousands to your initial costs. This analysis breaks down the current market to help you identify which lenders offer the most expatriate-friendly terms and how to secure a deal that protects your long-term interests.
We will explore the specific eligibility requirements for non-nationals, the differences between conventional and Islamic finance options, and the strategic steps you can take to improve your chances of approval. Whether you are a first-time buyer or looking to refinance an existing property, understanding the nuances of the Dubai lending environment is the first step toward securing your financial future in the desert.
Key takeaways
- Predictable Budgeting: Fixed rate terms in Dubai typically range from one to five years, providing a shield against EIBOR volatility during the initial phase of the loan.
- LTV Requirements: Expats can generally borrow up to 80% of the property value for their first home under 5 million AED, with the remaining 20% required as a down payment.
- Fee Awareness: Beyond the interest rate, expect to pay approximately 6-7% of the property value in upfront costs, including bank processing fees and Dubai Land Department charges.
- Reversion Rates: Always check the "follow-on" rate that applies after the fixed period ends, as this determines your long-term affordability.
How Fixed Rate Mortgages Work in the UAE
In the Dubai market, a "fixed rate" mortgage does not usually mean the rate is locked for the entire 25-year duration of the loan. Instead, lenders offer a fixed period, commonly for one, two, three, or five years. During this window, your interest rate remains constant regardless of what happens in the global financial markets. This provides a massive advantage for expats who are on a fixed salary and need to manage their household cash flow with precision.
Once the fixed period expires, the mortgage typically reverts to a variable rate. This variable rate is usually calculated as the 3-month or 6-month EIBOR plus a fixed margin set by the bank. For example, if the bank's margin is 2.5% and the EIBOR is 5%, your new rate would be 7.5%. Understanding this transition is essential because a low introductory fixed rate can sometimes mask a very expensive reversion rate later on.
The 3-Year vs. 5-Year Fix
The three-year fixed rate is currently the "sweet spot" for many Dubai expats. It offers enough time to ride out short-term economic cycles without the slightly higher interest premium often attached to five-year products. However, if you plan on staying in your property for a decade or more, paying a small premium for a five-year fix can provide significant peace of mind, especially in a rising interest rate environment.
Top Banks for Expat Mortgages in Dubai
While almost all major banks in the UAE offer products for expats, some have developed a reputation for being more flexible with non-national applicants. HSBC is often a top choice for high-income expats, particularly those who already have a global relationship with the bank. They offer competitive rates and a streamlined process for international transfers, though their eligibility criteria can be stricter than local banks.
Emirates NBD, the largest bank in Dubai, offers some of the most diverse mortgage products. They have a deep understanding of the local real estate market and often provide pre-approvals faster than their competitors. Their fixed-rate products are frequently updated to remain competitive with market trends, making them a staple for expat buyers.
Abu Dhabi Islamic Bank (ADIB) and Dubai Islamic Bank (DIB) are excellent options for those seeking Sharia-compliant financing. Instead of interest, these banks use a profit rate. For many expats, the "fixed profit rate" products function very similarly to a conventional fixed-rate mortgage, providing the same level of payment certainty while adhering to Islamic financial principles.
Eligibility and Loan-to-Value (LTV) Ratios
The Central Bank of the UAE sets strict limits on how much expats can borrow. If you are purchasing your first home in the UAE and the property value is less than 5 million AED, you can borrow up to 80%. This means you need a 20% cash down payment. If the property value exceeds 5 million AED, the maximum LTV drops to 70% for the first purchase.
For a second or third investment property, the requirements become even more stringent, with the LTV usually capped at 60%. These rules are designed to prevent market overheating, but they mean that expats must have significant liquid savings before they can even consider a mortgage application. You will also need to prove a stable income, usually through at least six months of bank statements and a salary certificate from your employer.
Minimum Salary Requirements
Most banks require a minimum monthly salary of 15,000 AED to 20,000 AED to qualify for a mortgage. Some niche products exist for those earning slightly less, but the interest rates are often higher. If you are self-employed, the documentation process is more rigorous, requiring two years of audited accounts and personal bank statements to prove the business's sustainability.
The Real Cost of Securing a Mortgage
When calculating your budget, the interest rate is only one part of the equation. Expats are often surprised by the upfront costs associated with a mortgage in Dubai. These costs are usually not rollable into the loan, meaning you need to have the cash ready at the time of purchase.
- Dubai Land Department (DLD) Fee: 4% of the property purchase price plus a small administrative fee.
- Property Registration Fee: Approximately 4,000 AED for properties over 500,000 AED.
- Mortgage Registration Fee: 0.25% of the loan amount paid to the DLD.
- Bank Processing Fee: Usually 1% of the loan amount, though this is often waived during promotional periods.
- Valuation Fee: Between 2,500 AED and 3,500 AED to have the bank's surveyor assess the property.
- Life Insurance: Mandatory in the UAE. The cost varies based on your age and health, but it is a recurring monthly or annual expense.
Comparing Fixed vs. Variable Rates
Why choose a fixed rate when variable rates might start lower? The answer lies in the "Stress Test." When you apply for a mortgage, the bank doesn't just check if you can afford the current rate; they check if you can still afford the payments if rates rise by 2% or more. A fixed rate eliminates this worry for the duration of the term.
Variable rates are often linked directly to the EIBOR. While they can be cheaper when interest rates are falling, they leave you exposed to sudden spikes. For an expat who might be sending money home or paying school fees in a different currency, the stability of a fixed rate is often worth the slightly higher starting percentage. It allows for a level of financial planning that variable rates simply cannot offer.
The Importance of Pre-Approval
In Dubai's fast-moving real estate market, a pre-approval letter is your most powerful tool. It tells sellers that you are a serious buyer with the financial backing to close the deal. A pre-approval typically lasts for 60 to 90 days and gives you a clear idea of your maximum budget. Without it, you might find your dream home only to lose it to a cash buyer or someone who already has their financing in place.
During the pre-approval process, the bank will scrutinize your credit report from the Al Etihad Credit Bureau (AECB). Any outstanding debts, such as credit card balances or car loans, will be factored into your Debt Burden Ratio (DBR). In the UAE, your total monthly debt repayments cannot exceed 50% of your monthly income. Reducing your credit card limits before applying can often increase the amount a bank is willing to lend you.
Early Settlement and Exit Strategies
Expats often have shorter time horizons than local buyers. You might plan to stay for five years, but career opportunities could take you elsewhere sooner. This is why the early settlement fee is a significant factor in choosing the best mortgage. UAE Central Bank regulations currently cap the early settlement fee at 1% of the outstanding loan or 10,000 AED, whichever is lower.
This cap is a major win for expats, as it makes it relatively affordable to sell the property or refinance if a better deal comes along. However, always double-check the terms in your specific contract, as some banks may have different structures for partial repayments versus full settlement. Knowing your exit strategy before you sign the mortgage deed can save you a lot of headache later.
FAQ
Can I get a mortgage in Dubai if I am not a resident?
Yes, many banks offer non-resident mortgages, but the terms are different. Typically, the LTV is lower, often capped at 50% or 60%, and the interest rates are higher than those offered to residents with a valid Emirates ID and residency visa.
Is life insurance mandatory for a Dubai mortgage?
Yes, life insurance is a legal requirement for getting a mortgage in the UAE. Most banks will insist you take their in-house insurance policy, but you can often save money by assigning a private policy to the bank, provided it meets their specific coverage requirements.
How long does the mortgage application process take?
The process from initial application to final offer can take anywhere from two to four weeks. Pre-approval is usually faster, often completed within 3 to 5 working days, provided all your documentation is in order.
What happens if I lose my job while I have a mortgage?
Losing your job can be stressful for an expat. Most banks have a grace period, but you must inform them immediately. Many buyers opt for job loss insurance as part of their mortgage package, which can cover your installments for a few months while you search for a new role.
Can I use my mortgage to buy an off-plan property?
Yes, but the rules are stricter. Banks usually only lend on off-plan properties from major, reputable developers and often require the construction to be at a certain stage (e.g., 50% complete) before they will release funds. Many off-plan buyers use developer payment plans and then switch to a mortgage upon completion.
Conclusion
Securing the best fixed rate mortgage in Dubai for expats requires a balance between a competitive interest rate and a thorough understanding of the associated fees and long-term terms. While the initial 20% down payment and 6-7% in closing costs represent a significant upfront investment, the stability of a fixed rate can provide a secure foundation for your life in the UAE. By focusing on lenders like HSBC or Emirates NBD and ensuring you have a solid pre-approval in hand, you can move from the uncertainty of the rental market to the security of property ownership. Always remember to look beyond the first few years and consider the reversion rate and settlement fees to ensure your investment remains sound for the duration of your stay in Dubai.